Introduction
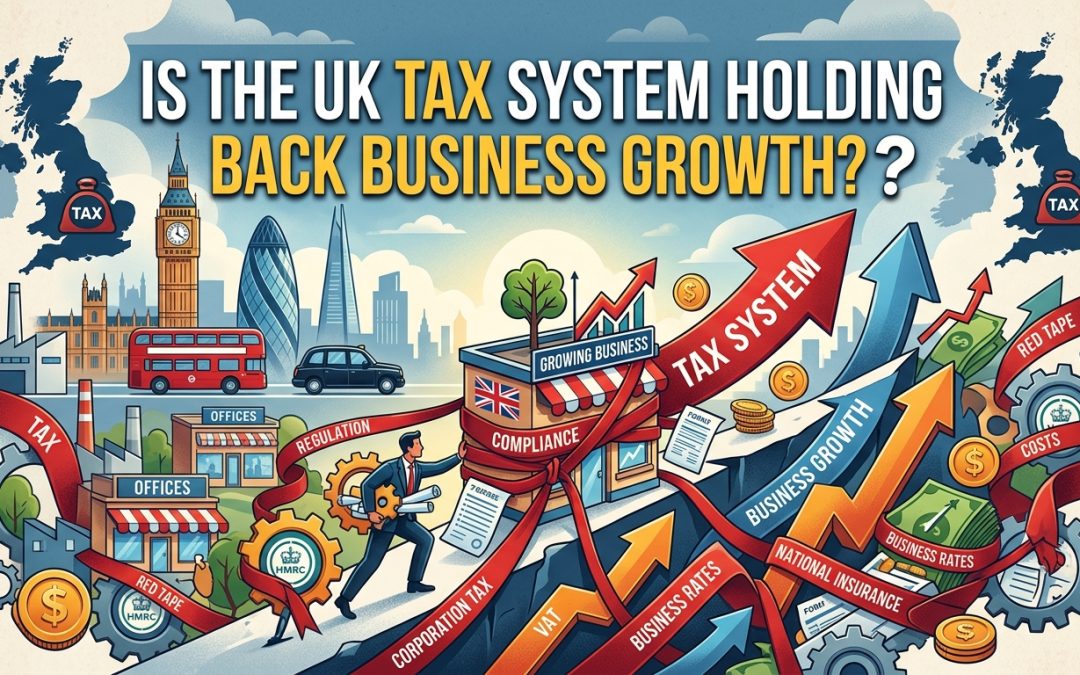
There is an important question hiding behind the UK’s debate about taxation: “Does the tax system simply raise revenue, or does it also influence whether businesses choose to grow?”
The distinction matters. Nobody seriously argues that businesses should pay no tax. Corporation Tax helps fund public services, employer National Insurance contributes to the cost of the welfare state, and VAT is an important source of government revenue. The question is whether the way these taxes are structured sometimes creates unintended incentives for businesses to remain small.
For an entrepreneur running a small business, growth is not simply about generating more sales. Growth can mean taking on employees, moving into larger premises, investing in technology, becoming VAT registered, increasing payroll costs and eventually facing a more complicated tax regime.
At each stage, the business can encounter another financial or administrative hurdle.
The problem with tax cliffs
One of the clearest examples is VAT.
A business below the VAT registration threshold has a relatively simple proposition. Once turnover crosses the threshold, however, the business enters a different tax and administrative environment. For some businesses, particularly those selling predominantly to consumers, becoming VAT registered can have a significant impact on pricing and margins.
The answer does not necessarily have to be a dramatically higher VAT threshold. A better approach could be a graduated system, where the tax burden increases progressively as turnover rises rather than changing suddenly at a particular point.
The principle should be straightforward: growing by another £1 should never make a business materially worse off.
The cost of employing people
Employment is another area where growth can become more expensive.
When a company takes on an employee, the salary is only part of the cost. Employer National Insurance, pension contributions and other employment costs increase the real cost of hiring.
For a small business contemplating its first few employees, this can be significant.
There is a strong economic argument for making the first stages of employment growth cheaper. Rather than applying the same approach throughout the economy, the government could consider a more graduated system, with greater support for the first few employees and a gradual movement towards the standard rate as companies become larger.
That would make the transition from sole trader to employer less intimidating.
Business rates and the cost of expansion
Business rates create another interesting problem because they can penalise physical expansion.
A successful retailer may need another shop. A manufacturer may need a larger factory. A technology company may need more office space. A logistics company may need a bigger warehouse.
Yet moving into larger premises can immediately increase the business’s tax bill.
This creates an awkward economic incentive. The more successful a business becomes, the more space it may require, and the greater its property-related tax burden becomes.
One possible solution would be a temporary “growth allowance”. Businesses expanding into substantially larger premises could receive relief on the additional business-rates liability for several years, allowing them time to generate the additional revenues needed to support the expansion.
Taxing profits versus encouraging investment
Corporation Tax presents a different issue.
The purpose of Corporation Tax is to tax company profits. But from an economic perspective, there is a difference between profits being extracted from a company and profits being reinvested in it.
A company retaining money to buy equipment, develop software, improve cybersecurity, train employees or enter a new market is doing something very different from a company simply distributing the money to shareholders.
The tax system could therefore do more to encourage reinvestment. Rather than simply cutting Corporation Tax across the board, the government could provide stronger incentives for qualifying investment and productivity improvements.
That would shift the emphasis from “how much tax does the company pay?” to “what is the company doing with the money it doesn’t pay in tax?”
Encourage entrepreneurs to build again.
There is also a broader question around Capital Gains Tax and entrepreneurship.
A successful entrepreneur may spend ten or twenty years building a company before selling it. If the proceeds are then reinvested into another business, that individual is effectively becoming an entrepreneur for a second time. The tax system could recognise this by allowing some capital gains to be deferred where the proceeds are reinvested into another qualifying UK business.
That could encourage a cycle of build, sell, reinvest and build again.
Simplification may be as important as tax cuts.
Perhaps the biggest opportunity, however, is simplification. Large businesses can employ tax specialists, accountants and lawyers. A small business owner often cannot.
A tax system containing numerous thresholds, reliefs, exceptions and temporary schemes can therefore have a disproportionately large impact on smaller businesses. The government should aim for a system that a reasonably competent business owner can understand without needing professional advice simply to determine what they owe.
A tax system designed for growth
The answer is therefore not necessarily lower taxes everywhere but it is about designing taxation around the economic behaviour we want to encourage.
The UK could aim for a system in which there are no damaging tax cliffs, employment is encouraged, investment is rewarded, physical expansion is supported, entrepreneurship is not unnecessarily penalised, and compliance is straightforward.
Businesses should not be given a tax-free ride but neither should the tax system inadvertently make staying small financially attractive.
The real test of a business tax system should therefore be more ambitious than asking how much revenue it raises. It should also ask “does it encourage businesses to invest, employ, innovate and grow?” If the answer is sometimes “no”, then reform does not necessarily require a wholesale reduction in taxation. It may simply require the government to make growth itself a more attractive outcome.
Recent Comments